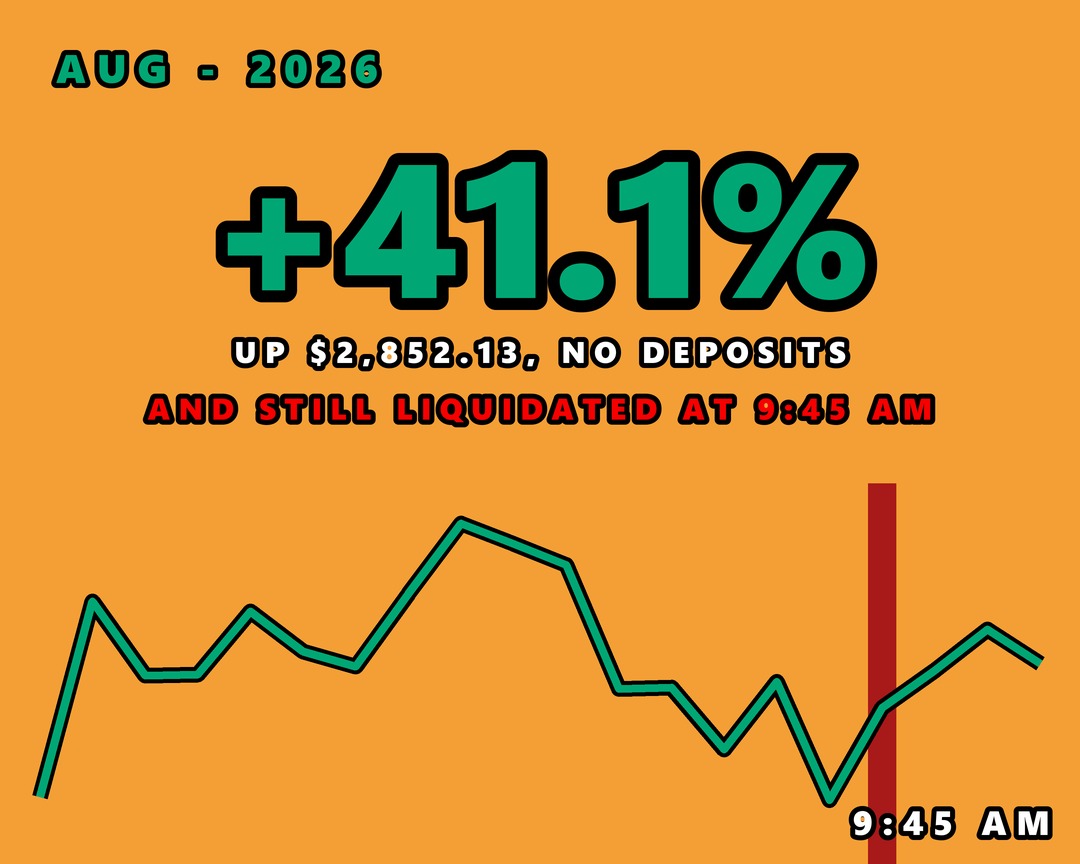
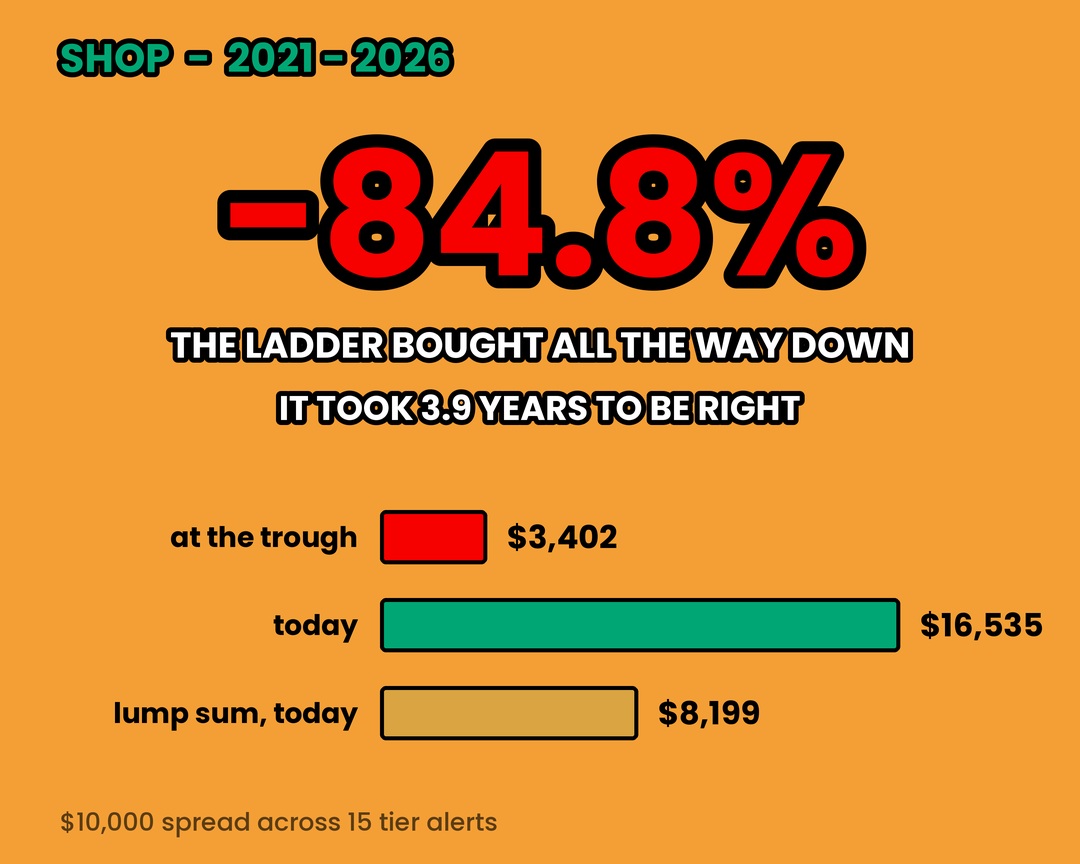
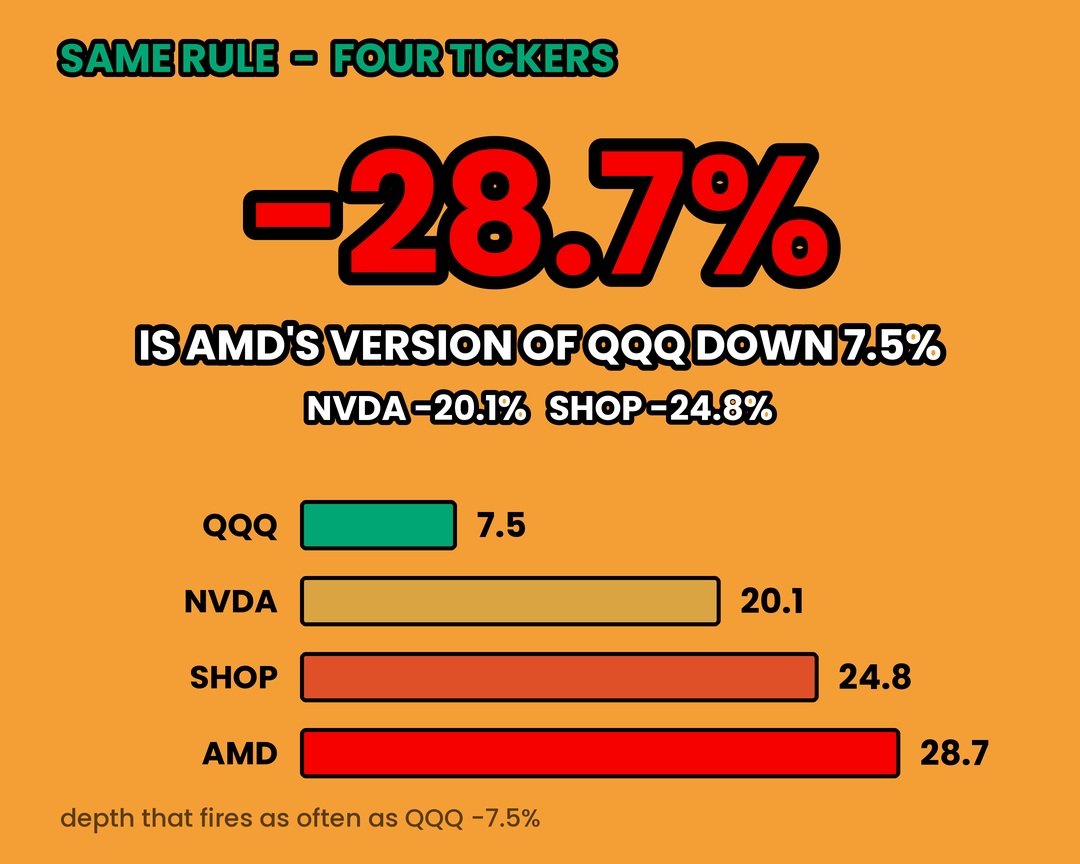
Quick disclosure: this is a personal trading journal, not investment advice. I trade at tastytrade with my own money. No affiliate links here, no broker or prop firm deals. Read the full disclaimer.
Part 1 of 3 in the FOMC study. Read part 2, the research →
I want to be straight about how this started, because the honest version is worse than the version I almost wrote.
I did not have a thesis. I did not have a system. It was FOMC week and I decided to gamble.
That's it. That's the whole setup.
Trade Summary
Well — there was a reason. Just not a good enough one for the size I took.
The market had been grinding down since June. And on the Friday my dipSignal fired.
dipSignal is a script I built a few weeks ago. It came out of a different experiment: I backtested just holding TQQQ and autobuying it on a schedule, buying straight through the highs and the lows without thinking about it. The backtest said $50 a week into TQQQ from 2010 would have turned into something absurd, with an 82% drawdown on the way.
But an autobuy only answers how often. It doesn't answer when should I put extra in. So I wrote dipSignal to tell me when things were properly on sale.
It watches QQQ, works out how far below its recent high the price is, and emails me when that gap crosses a threshold. Three tiers. MINOR at −7.5%. MODERATE at −10%. CRASH at −15%, then again every 5% deeper.
That's the whole thing. No trend filter.
What those tiers actually go on to do is something I only measured later, and the numbers my own alert was quoting turned out to be from a rule I had stopped using.
And the timing felt perfect. I finish building a tool that tells me when the market is on sale, and within weeks the market obliges by going down. Of course I was going to use it for something.
Here's the comment I wrote at the top of my own file:
Three MECHANICAL tiers based purely on drawdown from the recent high, ANY trend (no 200-day filter). Descriptive, not a prediction:
Descriptive. Not a prediction.
I wrote that. A few weeks later I used it as a prediction.
On Friday the 24th, QQQ closed 8.3% off that high. Monday the 27th, the day I bought, 8.6%. That's the MINOR tier. The shallowest one. The one the alert email I got that week describes like this:
A minor pullback (the −7.5% tier). Common and usually shallow — most bounce, some deepen toward −10% / −15%. A small nibble, or simply waiting for a deeper tier, are both reasonable.
A small nibble.
This is a tool I built to size extra share purchases on top of a weekly autobuy. I read "a small nibble" and I bought two /MNQ futures at 95% buying power usage.
A drawdown gauge tells you where you are. It does not tell you where you're going. I built a ruler and used it as a crystal ball.
Monday
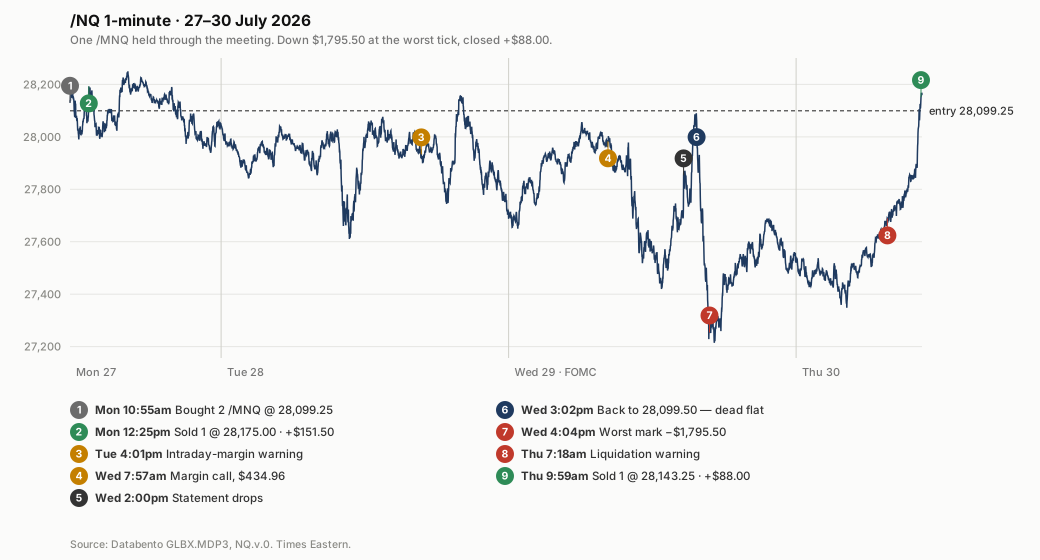
10:55 AM. Bought 2 /MNQU6 at 28,099.25.
Sold one back at 12:25 PM for 28,175.00. Up 75.75 points, +$151.50. Thank you and good night.
The other one I held. Because the Fed was Wednesday and I wanted to be in it.
By 3:33 PM that contract was worth +156.50 points. Three hundred and thirteen dollars sitting right there. Didn't take it.
Monday's close: +$186.00 unrealized. Comfortable.
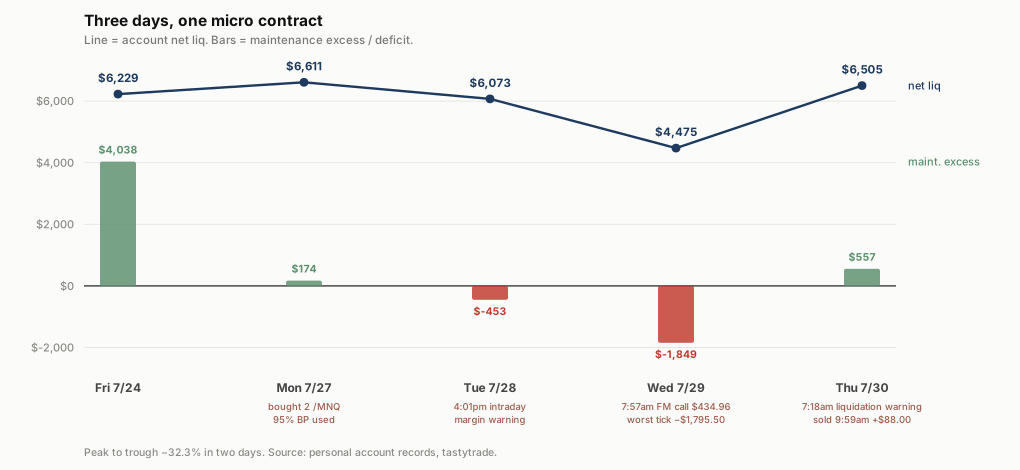
Here's the number I should have been looking at instead. My buying power usage was $6,279.18 against a net liq of $6,611.25.
Ninety-five percent.
I had $348.64 of buying power left and a Fed meeting in two days. I wasn't positioned. I was committed.
Tuesday, 4:01 PM
Our records indicate that you are currently using intraday futures margin. If you don't liquidate or your account is unable to cover the overnight requirements, intraday futures margin will be temporarily suspended until the account closes with a margin surplus. Additionally, our futures risk team may close position(s) on your behalf between 3:00-4:00 pm CT.
That's tastytrade. In my inbox. Tuesday afternoon.
Tuesday's close: net liq $6,073.29, and my maintenance excess had gone negative. −$452.92.
My broker was telling me, one day before the Fed, that they might close my position for me.
What did I do about it? Nothing.
Wednesday, 7:57 AM
Your account ending in 425 has been issued a Futures Maintenance (FM) call for $434.96 from trade date 2026-07-28 due by the end of the day on 2026-07-29.
Four hundred and thirty-four dollars and ninety-six cents. Due by end of day. Which was FOMC day.
I read that at breakfast and thought: it'll sort itself out today.
That is the single dumbest sentence in this entire post and I'm leaving it in.
Wednesday, 2:00 PM
The Fed held at 3.50–3.75%. The vote was 9–3, and all three dissenters wanted a quarter-point hike.
Hawkish. The tape knew instantly.
At 2:00 PM exactly, /NQ printed a bar from 27,723.00 to 27,853.00 on 5,213 contracts, close to four times the session's median minute. High of 27,888.50 two minutes later.
Then by 2:25 PM it was back to 27,727.50. The whole pop given back in twenty-three minutes.
Then the press conference started and it rallied. At 3:02 PM /NQ traded 28,099.50.
My entry was 28,099.25.
Dead flat. A quarter point green. Three days of white-knuckling and I was exactly where I started, with a margin call due that day and the position back at break-even.
I didn't close.
By 3:24 PM the Dow was down more than 840 points. The 30-year yield was up over 9bp to 5.193%. The Nasdaq-100 went into correction on the day.
The closing minute traded 10,612 contracts. Wednesday's close put me at −$1,528.50 on the contract, and the account at:
Net liq $4,475.27, down from $6,611.25 Monday. Down 32.3% in two days.
Cash balance −$990.10. Maintenance excess −$1,848.91. Buying power −$3,697.83.
Every number negative except the net liq, and that one had lost a third of itself.
4:04 PM
Four minutes after the bell, /NQ printed 27,201.50.
897.75 points below my entry. On one micro contract that is −$1,795.50.
One /MNQ, a tenth the size of the full contract. That is 27.2% of Monday evening's balance, and 40% of what was left by Wednesday.
I want you to sit with the timing, because I didn't understand it until days later.
4:04 PM was the overnight low. The bottom. AS I WRITE THIS A MONTH LATER, THE MARKET HAS NOT BEEN LOWER SINCE.
My maximum pain and the actual bottom were the same minute. I had no idea. At 4:04 PM I was bracing for it to get worse all night.
Thursday, 7:18 AM
Your account ending in 425 has an excessive margin deficit… If we do not see a sufficient deposit on our system or hear from you, then we may have to liquidate. We will make an effort to wait at least 30 minutes before taking action if deemed necessary, but we may need to liquidate sooner depending on market conditions.
Thirty minutes.
At 9:59 AM tastytrade sold it for me at 28,143.25. Up 44.00 points. +$88.00.
I didn't even place the exit. They did. Badly wounded, but out.
And it wasn't skill, and it wasn't the Fed. Microsoft reported Wednesday after the bell — cloud revenue up 43%, best since 2022, stock up about 17% overnight. That's what carried me back over my entry.
I didn't escape. I got carried out by Satya Nadella.
Takeaways
- Position size is what made a bad idea dangerous, not the idea. "Oversold, so it bounces" is a mediocre thesis. Held small, a mediocre thesis costs you a mediocre amount. I held it at 95% buying power usage into a Fed meeting, and it generated three emails from my broker in three days and took a third of the account in forty-eight hours. One micro contract did that. Not ten. One. 95% BP usage means you have already decided you can't be wrong. I have done the larger version of this before, with one /NQ and a stop I removed mid-trade, and the lesson did not transfer on its own.
- A trade working is not the same as being right. The contract I held for the "pattern" made 31.75 points less than the identical contract I closed on Monday for no reason at all. If you can't separate "it worked" from "my reason was correct," every lucky trade quietly makes you a worse trader.
- Read your own tools. My alert said "a small nibble." I bought futures on margin. The tool wasn't wrong. I just heard what I wanted.
The trade
Bought 2 /MNQU6 on 7/27 at 10:55 AM — 28,099.25
Sold 1 on 7/27 at 12:25 PM — 28,175.00 — +$151.50
Best unrealized mark, 7/27 3:33 PM — 28,255.75 — +$313.00
Worst tick, 7/29 4:04 PM — 27,201.50 — −$1,795.50
tastytrade sold 1 for me on 7/30 at 9:59 AM — 28,143.25 — +$88.00
Net on the two contracts: +$239.50 gross, before fees. Peak drawdown on the survivor: −$1,795.50, which was 27.2% of Monday's net liq and 40% of Wednesday's.
EOD: +$239.50 | peak drawdown −$1,795.50
Here's the part I didn't expect.
Thursday afternoon, out of the position, hands still shaky, I started thinking about other Fed meetings. And a pattern assembled itself in my head, fully formed, feeling like something I'd always known.
So I spent $11 finding out whether it was real.
→ Part 2: I spent $11 to find out my pattern wasn't real
Catch you next week.
I trade futures and options at tastytrade with my own money. I earn nothing if you open an account there. The link is just so you know where these fills come from.
Get the next one
I publish every test I run, including the ones that prove me wrong. If that is worth something to you, join the mailing list and the next one lands in your inbox.
Growing Tendies does not accept any liability for any loss or damage which is incurred from any loss of money on a trade. All trades are done using the tastytrade platform.